
Branded Residences & Luxury Living: The Numbers, Trends, and Due Diligence Behind the Boom
Branded Residences & Luxury Living: The Numbers, Trends, and Due Diligence Behind the Boom
A decade ago, buying a "branded residence" meant purchasing an apartment attached to a five-star hotel like a Four Seasons or a Ritz-Carlton. You paid extra for 24-hour room service, daily housekeeping, and a recognisable concierge desk downstairs.
The market in 2026 operates on an entirely different scale. Branded schemes now span fashion houses (Armani, Missoni, Elie Saab), automotive badges (Porsche, Aston Martin, Bugatti), and high-end culinary names. Globally, the sector has grown by over 180% in the last ten years, with more than 900 active schemes operating worldwide and hundreds more in the contracted pipeline (Source: Savills Global Residential Development Consultancy / ArentFox Schiff).
High-net-worth buyers treat these developments as a distinct asset class combining lifestyle hospitality with portfolio capital preservation. The pricing premiums, the rise of standalone non-hotel developments, operational fee models, and practical risks require careful review before committing millions to a branded deed.
What Exactly Is a Branded Residence?
At its core, a branded residence is a residential property that is developed, designed, and operated under a formal licence agreement with a recognised premium brand.
These developments fall into two primary formats:
- Hotel-Integrated Residences: Private units co-located within or directly adjacent to a working luxury hotel. Owners share hotel infrastructure (spas, concierge desks, valet, dining venues) and can often place their properties into an operator-managed rental pool when not in residence.
- Standalone Branded Developments: Residential-only towers or enclaves with no commercial hotel on-site. The brand provides architectural and interior design curation, operational staffing standards, and bespoke services through dedicated residential management teams. According to Knight Frank’s Residence Report, standalone developments now account for roughly 30% of the global development pipeline, up from just 18% among completed projects.
The Branded Premium: What Do Buyers Actually Pay?
The defining characteristic of the branded sector is the price premium buyers pay over comparable, non-branded luxury properties in the same submarket.
Globally, branded residences command an average premium of 33% over equivalent prime stock (Source: Savills Branded Residences Research). However, this figure fluctuates significantly depending on location type and market maturity:
| Market Category | Average Price Premium Over Non-Branded Stock | Market Characteristics | Source Benchmark |
| Global Average | ~33% | Aggregate baseline across urban and resort locations globally | Savills |
| Resort Destinations | ~39% | Driven by holiday-let pooling, managed beach clubs, and seasonal scarcity | Savills |
| Established Gateway Cities | 25% to 32% | Mature prime markets like London, Miami, and New York with deep resale liquidity | Knight Frank / Savills |
| High-Growth Emerging Hubs | 35% to 47%+ | Premium reflects strong trust in brand execution against unbranded local builds | Savills |
In resort markets-such as Phuket, Marbella, or coastal destinations across the Mediterranean-the premium expands because private buyers will pay for effortless "lock-and-leave" management while away. In emerging cities, the brand acts as a badge of construction quality and legal delivery, creating a steeper price gap against standard private developers.
Key Drivers: Why Buyers and Developers Choose the Model
The explosion of branded living comes down to aligned incentives on both sides of the transaction:
1. The Investor & Homeowner Perspective
- Turnkey Maintenance & Lock-and-Leave Security: For ultra-high-net-worth individuals owning homes across three or four countries, keeping a property operational is a headache. An on-site management team ensures the property is maintained, inspected, and fully staffed year-round.
- Higher Rental Demand and Daily Rates: In properties with managed rental programmes, the brand's global reservation system channels high-spending guests directly to your unit, often achieving day rates 15% to 30% higher than unbranded luxury holiday rentals.
- Secondary Market Liquidity: Resale data in established markets shows that branded residences retain liquidity better during market pullbacks. In Miami, for instance, branded units in Brickell and Edgewater achieved resale premiums 18% to 22% above adjacent unbranded towers (Source: Savills Prime Residential Markets).
2. The Developer Perspective
For developers, licensing a marquee brand speeds up sales absorption, allows project financing to clear faster, and justifies a substantial sales premium per square foot that more than offsets the licensing and royalty fees paid to the brand operator.
Global Hotspots: Where Branded Schemes Concentrate
While North America remains the largest historic market (holding roughly 32.7% of completed global schemes), the development pipeline has shifted heavily toward the Middle East, Asia-Pacific, and southern Europe (Source: Knight Frank):
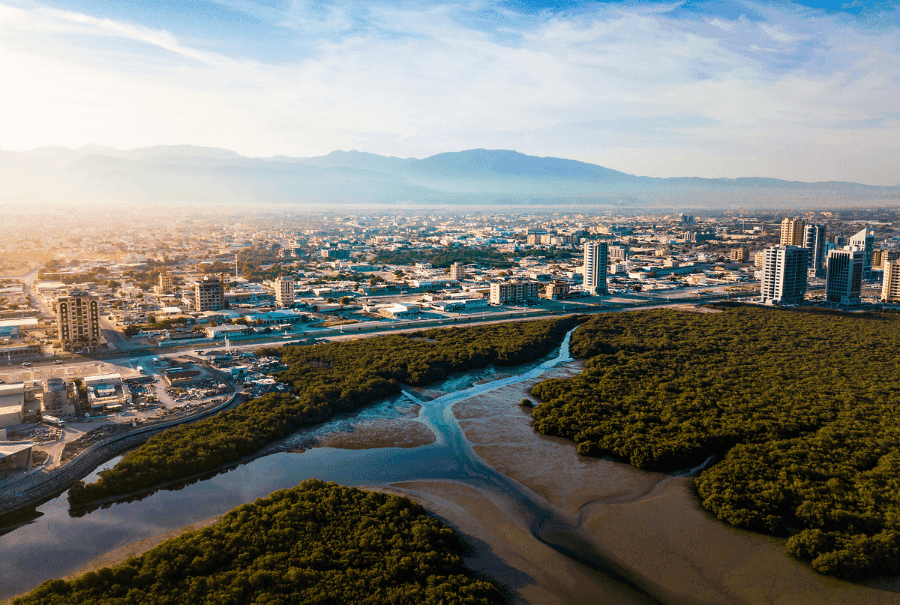
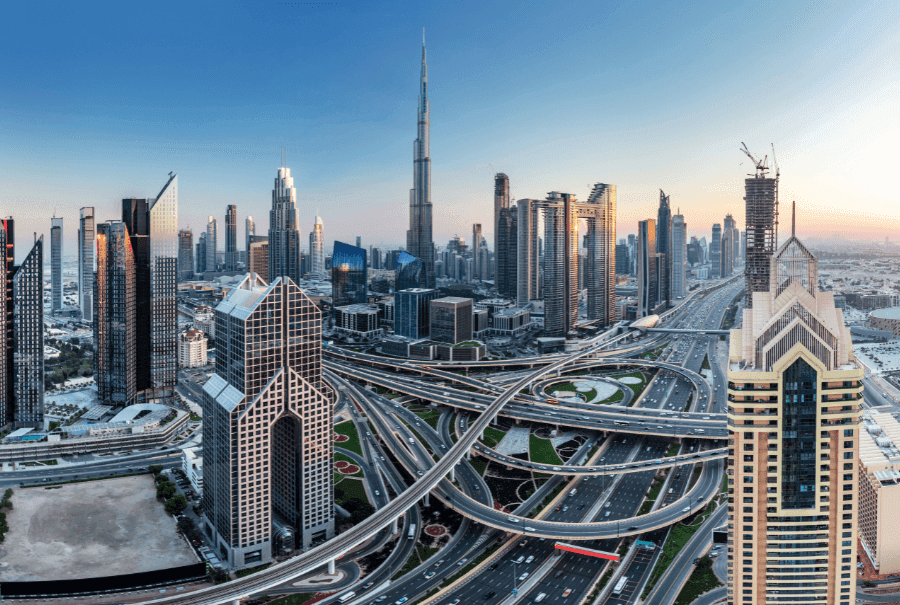
- Dubai & the Northern Emirates: Dubai represents the single densest branded residential market on earth, with more than 140 active or planned projects. Neighbouring Ras Al Khaimah has rapidly followed suit along Al Marjan Island and RAK Central, attracting brands like Nobu, Nikki Beach, and Radisson Blu alongside the development of the $5.7 billion Wynn integrated resort. Over the past five years, branded inventory across the Middle East and North Africa expanded by 187% (Source: Savills).
- Miami & South Florida: Accounting for the highest volume of automotive and fashion-branded towers in the West, driven by domestic tax migration and deep Latin American private capital.
- Asia-Pacific: Markets such as Thailand, Vietnam, and India recorded a 55% increase in branded projects over a five-year tracking window, focused heavily on coastal wellness and golf estates (Source: Savills).
The Reality Check: Hidden Costs and Due Diligence
Branded residences are not an automatic guarantee of financial outperformance. Buying into a branded address introduces specific cost structures and operational rules that investors must evaluate:
- Substantial Service Charges: Keeping hotel-grade concierges, valets, private chefs, and common amenities operational costs real money. Annual service charges in branded towers typically range between $5.00 and $15.00 per square foot (or AED 30 to AED 65+ per square foot in the Gulf). On a 2,000-square-foot residence, ongoing building fees can reach $10,000 to $30,000 annually before accounting for private utility bills or interior repairs.
- Net Yield Compression: A property marketing a 7.5% gross rental yield can quickly compress down to a 3.8% to 4.5% net yield once you deduct brand licensing levies, master community service charges, and rental pool revenue splits.
- Hospitality vs. Lifestyle Licensing: There is a critical difference between a hotel-backed residence and a licensing partnership with a fashion label. A hotel brand (like St. Regis or Mandarin Oriental) typically manages the property under long-term, 20- to 30-year operational contracts. In contrast, a fashion or automotive brand may simply be licensing their aesthetic for an upfront royalty fee, leaving building maintenance to a third-party management firm.
- Fit-Out & Furniture Replacement Reserves: If you enrol in the developer's official rental programme, you are typically required to buy the brand's approved furniture package. Operators often enforce strict refurbishment cycles every 5 to 7 years, requiring owners to pay for complete interior overhauls to maintain brand standards.
Explore Branded Living with BNW Developments
If you are evaluating branded residences in the region, selecting developments backed by established global hospitality and lifestyle names is the most reliable way to secure turnkey rental demand and long-term liquidity.
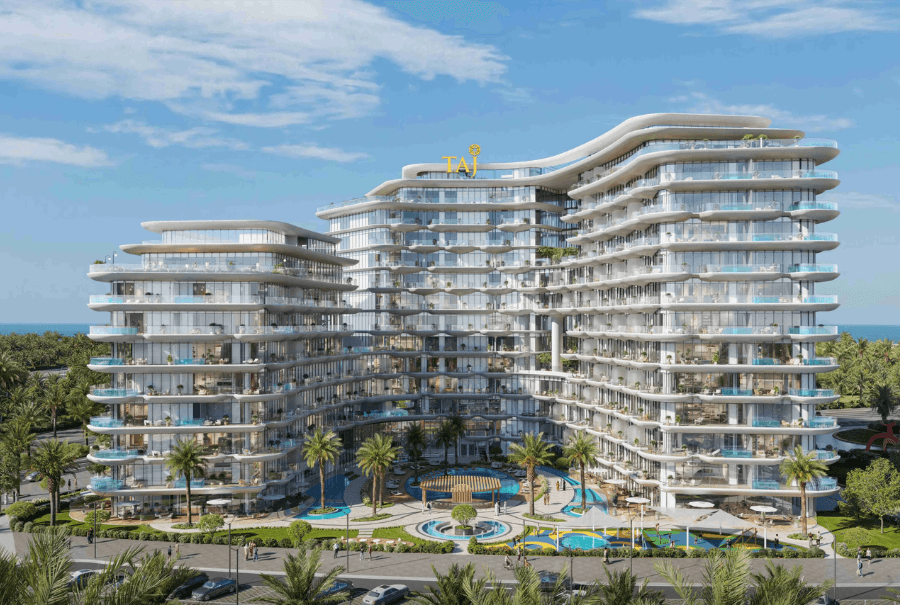
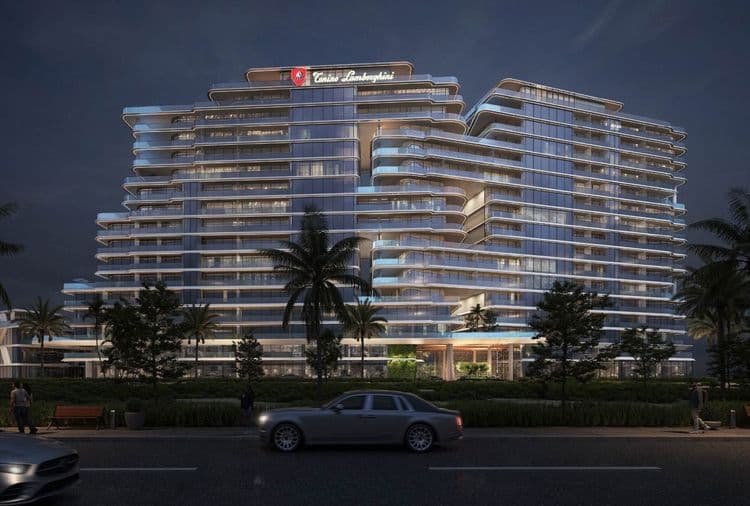
BNW Developments is leading this shift across the UAE with an AED 32B+ portfolio of branded and luxury residential projects. By pairing master-planned coastal addresses on Al Marjan Island with world-renowned names—including Tonino Lamborghini Residences and Taj Wellington Mews—as well as urban branded hubs like the Radisson Blu Hotel & Residences in RAK Central, BNW builds spaces designed from the ground up for high-yield returns and effortless living. Every project combines architectural pedigree and professional on-site management with structured developer payment plans and full qualifying access to the 10-Year UAE Golden Visa.
Connect with the BNW Developments advisory team today to explore current launch pricing, private floor plans, and projected yields across our branded portfolio.
Explore Branded Residences in UAE
Frequently Asked Questions
Can I live in my branded residence full-time?
Yes. Unless a development is explicitly designated as a hotel-room investment with statutory owner-usage caps, buyers have full freehold rights to occupy their residence year-round as their primary home.
Are standalone branded residences cheaper to run than hotel-integrated ones?
Generally, yes. Standalone residential towers avoid the heavy overheads associated with running a 24-hour commercial hotel (such as banqueting halls and expansive hotel lobbies), often resulting in lower annual service charges while retaining dedicated residential concierges and private resident facilities.
Do branded residences appreciate faster than normal luxury property?
Not necessarily. While they show higher price resilience during downturns and clearly appreciate faster at resale, their initial purchase price already includes a 30%+ premium. Capital appreciation depends on the underlying location, construction quality, and whether that brand premium holds up in the secondary resale market.