
UK vs. UAE Real Estate: Investment Comparison
For generations, British property has been associated with long-term wealth creation. From London apartments to family homes in Manchester and Birmingham, the UK offers an established market supported by familiar legal structures and consistent housing demand.
The UAE presents a different proposition. Its tax-free international business environment, expanding residential communities and growing selection of waterfront developments have attracted investors looking beyond traditional property markets.
For anyone weighing UAE vs UK real estate, the question isn't simply where property costs less. It's how each market fits an investor's financial objectives, income expectations and plans for the future.
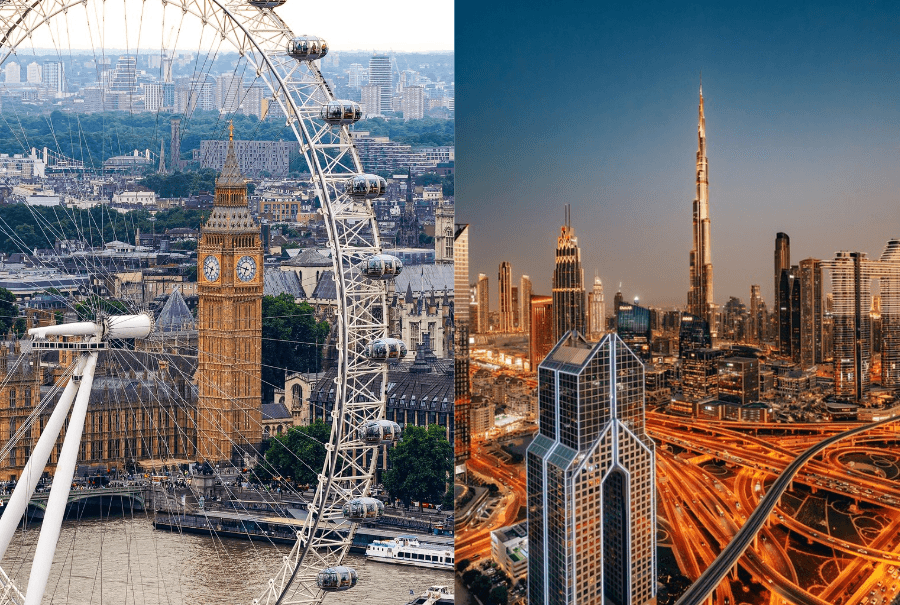
UAE vs UK Property Investment: Key Differences
| Factor | United Kingdom | UAE |
| Property market | Established, with substantial regional variation | Established urban markets and emerging destinations |
| Foreign ownership | Generally open to overseas buyers | Available in designated ownership areas |
| Purchase taxes and fees | Stamp duty or equivalent property transaction taxes | Emirate-specific registration and transfer fees |
| Rental income taxation | Generally subject to UK tax | Qualifying personal investment income generally outside UAE corporate tax |
| Property choices | Urban apartments, suburban homes, regional housing | Apartments, villas, waterfront and branded residences |
| Investment considerations | Regional demand, financing, regulation | Location, supply, service charges and developer quality |
Both markets offer opportunities, but their ownership costs and regulatory environments deserve closer examination.
Property Prices: Established Markets and Emerging Locations
The UK property market is far from uniform. According to the Office for National Statistics, the average UK house price was approximately £273,000 in July 2026, representing annual growth of 1.4%. However, national averages conceal significant differences between London, regional cities and smaller towns. (Source: Office for National Statistics, September 2026)
The UAE requires a similarly location-specific approach.
Dubai Marina and Downtown Dubai serve different buyers from suburban villa communities. Meanwhile, Ras Al Khaimah offers an expanding residential landscape, particularly around Al Marjan Island and RAK Central.
Investors should compare properties of similar size, specification and location rather than assuming one country's housing market is universally more affordable.
Rental Income: Looking Beyond Headline Yields
Rental returns are central to many property investment decisions.
In the UK, the ONS reported average monthly private rent of £1,400 in August 2026, up 3.8% year on year. (Source: ONS). Yet rental income alone reveals little about profitability. A property's actual return depends on its purchase price, vacancy periods, maintenance, management fees, financing and taxation. The same principle applies in the UAE.
Dubai's established residential neighbourhoods may attract long-term tenants, while resort destinations such as Al Marjan Island can also appeal to buyers exploring holiday-home opportunities.
Rather than comparing advertised rental yields, investors should calculate net returns using realistic operating expenses and occupancy assumptions.
Property Taxes and Transaction Costs
Taxation is among the most consequential differences between the markets.
UK Property Taxes
Buyers purchasing residential property in England and Northern Ireland may pay Stamp Duty Land Tax (SDLT), calculated through progressive bands. Higher rates generally apply to additional residential properties, while qualifying non-UK residents face a further 2 percentage-point surcharge. Scotland and Wales operate separate property transaction tax systems.
Rental income from UK property is generally taxable in the UK, including when the landlord lives overseas. Capital Gains Tax may also apply when selling an investment property. (Sources: HMRC – Stamp Duty and Non-Resident Landlords Scheme)
UAE Property Taxes
Dubai's property sale registration fee is 4% of the transaction value, with additional trustee, administrative and brokerage charges where applicable.
The UAE generally does not impose personal income tax on individuals. Rental income earned from personally held property may also fall outside UAE corporate tax when it meets the applicable investment-income conditions.
However, investors who remain UK tax residents may still have UK tax obligations on overseas income and gains. (Sources: Dubai Land Department and UAE Federal Tax Authority)
Cross-border tax advice is particularly important before purchasing through companies or relocating between jurisdictions.
Living in UAE vs UK: What Changes?
Property investment decisions often overlap with relocation plans.
When comparing living in UAE vs UK, climate, education, healthcare, transport and housing preferences all become relevant.
The UK offers established public services, extensive rail networks and a wide range of residential environments, from major cities to countryside communities.
The UAE offers a different lifestyle, characterised by international communities, modern residential developments, coastal recreation and year-round access to hospitality and leisure facilities.
Dubai appeals to those who enjoy metropolitan living. Abu Dhabi provides established family neighbourhoods, while Ras Al Khaimah offers beaches, mountains and a more relaxed coastal environment.
Cost of Living in UAE vs UK
Neither destination has a single cost-of-living figure that accurately represents every household.
London differs considerably from Leeds, just as central Dubai differs from Ras Al Khaimah.
| Household Expense | UK Considerations | UAE Considerations |
| Housing | Location, council tax, property type | Location, rent, housing fees and service charges |
| Education | State and private school options | Public-school eligibility and private-school fees |
| Healthcare | NHS eligibility and private cover | Mandatory or employer-provided insurance arrangements |
| Transport | Public transport, fuel, vehicle costs | Metro availability, car ownership and commuting |
| Utilities | Heating and energy expenses | Air-conditioning and seasonal electricity use |
The most meaningful comparison uses an actual household budget, accounting for salary, benefits, dependants and preferred neighbourhood.
Life in the UK vs the UAE: Long-Term Priorities
For investors considering a permanent move, life in the UK vs the UAE involves more than financial calculations.
The UK may offer familiarity, established professional networks and proximity to family.
The UAE can appeal to internationally mobile professionals seeking business opportunities, contemporary residential communities and a different lifestyle.
Residency arrangements also matter. Buying property in either destination does not automatically guarantee immigration status, although qualifying UAE property investments may support certain long-term residency applications.
Which Property Market Fits Your Investment Goals?
The UK offers a mature residential market with extensive historical data and established legal frameworks. The UAE provides international investors with access to diverse residential developments, including emerging waterfront destinations.
For buyers interested in the UAE, developers such as BNW Developments offer opportunities to explore premium and branded residences in Ras Al Khaimah, including projects on Al Marjan Island.
Ultimately, a successful property investment depends on choosing the right asset, understanding its costs, and aligning ownership with a realistic financial plan.
Whether considering a British buy-to-let property or a waterfront residence in the UAE, informed decisions begin with looking beyond the purchase price.